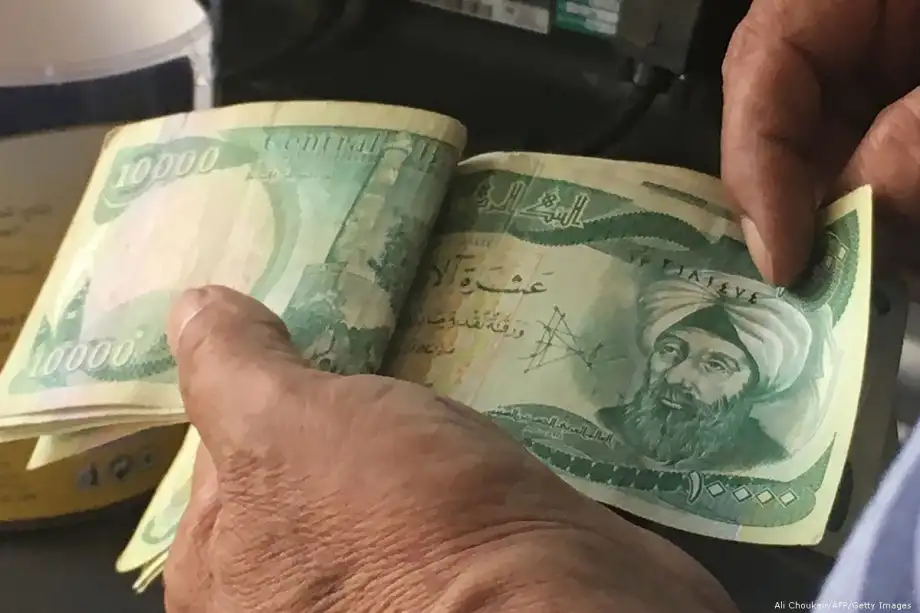

Iraq has devalued its national currency as the ongoing Middle East conflict puts increasing pressure on oil exports and government finances.
The Central Bank of Iraq announced a new official exchange rate for the dinar against the US dollar. The move comes as the country faces falling foreign currency reserves and growing economic challenges.
Under the new decision, the US dollar will be sold to the public at 1,520 Iraqi dinars. The previous official rate stood at 1,320 dinars per dollar and had remained in place since February 2023.
Financial institutions were instructed to stop using the previous exchange rate and adopt the new rate from October 7.
The currency adjustment follows major disruption to Iraq’s oil exports.
Crude oil sales generate nearly 90 percent of Iraq’s government revenue. However, exports have been affected since conflict between Iran and the United States intensified in February.
The fighting has disrupted shipping through the Strait of Hormuz, a vital route for energy exports from the region.
Iraq is also facing higher consumer prices as economic pressure spreads across the country.
Foreign currency reserves have reportedly fallen by around $20 billion. This has increased concerns over Iraq’s ability to support imports and maintain currency stability.
Oil-generated foreign currency remains essential for Iraq’s economy. The government depends on these revenues to finance imports and pay salaries to public sector employees and pensioners.
The latest devaluation highlights Iraq’s vulnerability to regional instability and disruptions in global energy trade. Continued pressure on oil exports could create further challenges for government finances, inflation and the country’s broader economic outlook.