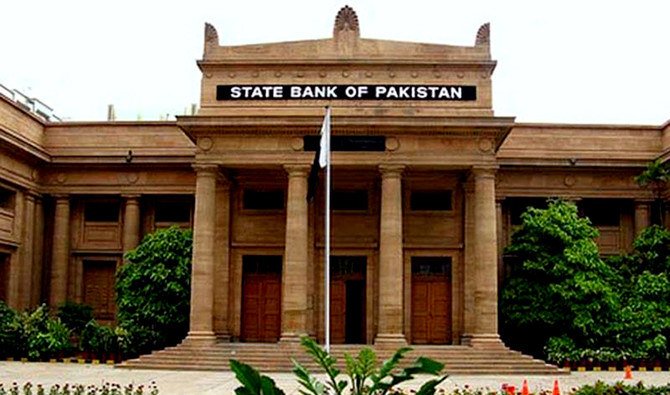

ISLAMABAD: Pakistan’s foreign exchange reserves have climbed to a record $26.864 billion despite economic uncertainty and rising oil prices caused by the ongoing Gulf war, according to the State Bank of Pakistan (SBP).
The country’s total reserves increased by $110 million during the week, compared with $26.754 billion recorded in the previous week.
The SBP reported that its foreign exchange reserves rose by $39 million, while commercial banks recorded an increase of $70 million.
Pakistan’s reserves have strengthened considerably since February, when the Gulf conflict began. At that time, the central bank held approximately $16.568 billion in reserves.
By October 30, the SBP’s holdings had increased to $21.568 billion, reflecting an improvement of more than $5 billion.
Financial sector experts believe the current reserve position provides sufficient support for exchange-rate stability and strengthens confidence among exporters and importers.
However, currency experts have raised concerns about the rupee’s perceived overvaluation, arguing that it makes imports cheaper and contributes to the widening trade deficit.
Pakistan recorded a trade deficit of $14.6 billion during July-October of fiscal year 2026-27. Imports reached $26 billion, while exports stood at $11.4 billion.
Experts have also highlighted the importance of developing policies to utilise overseas workers’ remittances more effectively.
For the latest updates, visit and follow The Truth International website (www.thetruthinternational.com), subscribe to the YouTube channel, and follow the Instagram and Facebook pages.